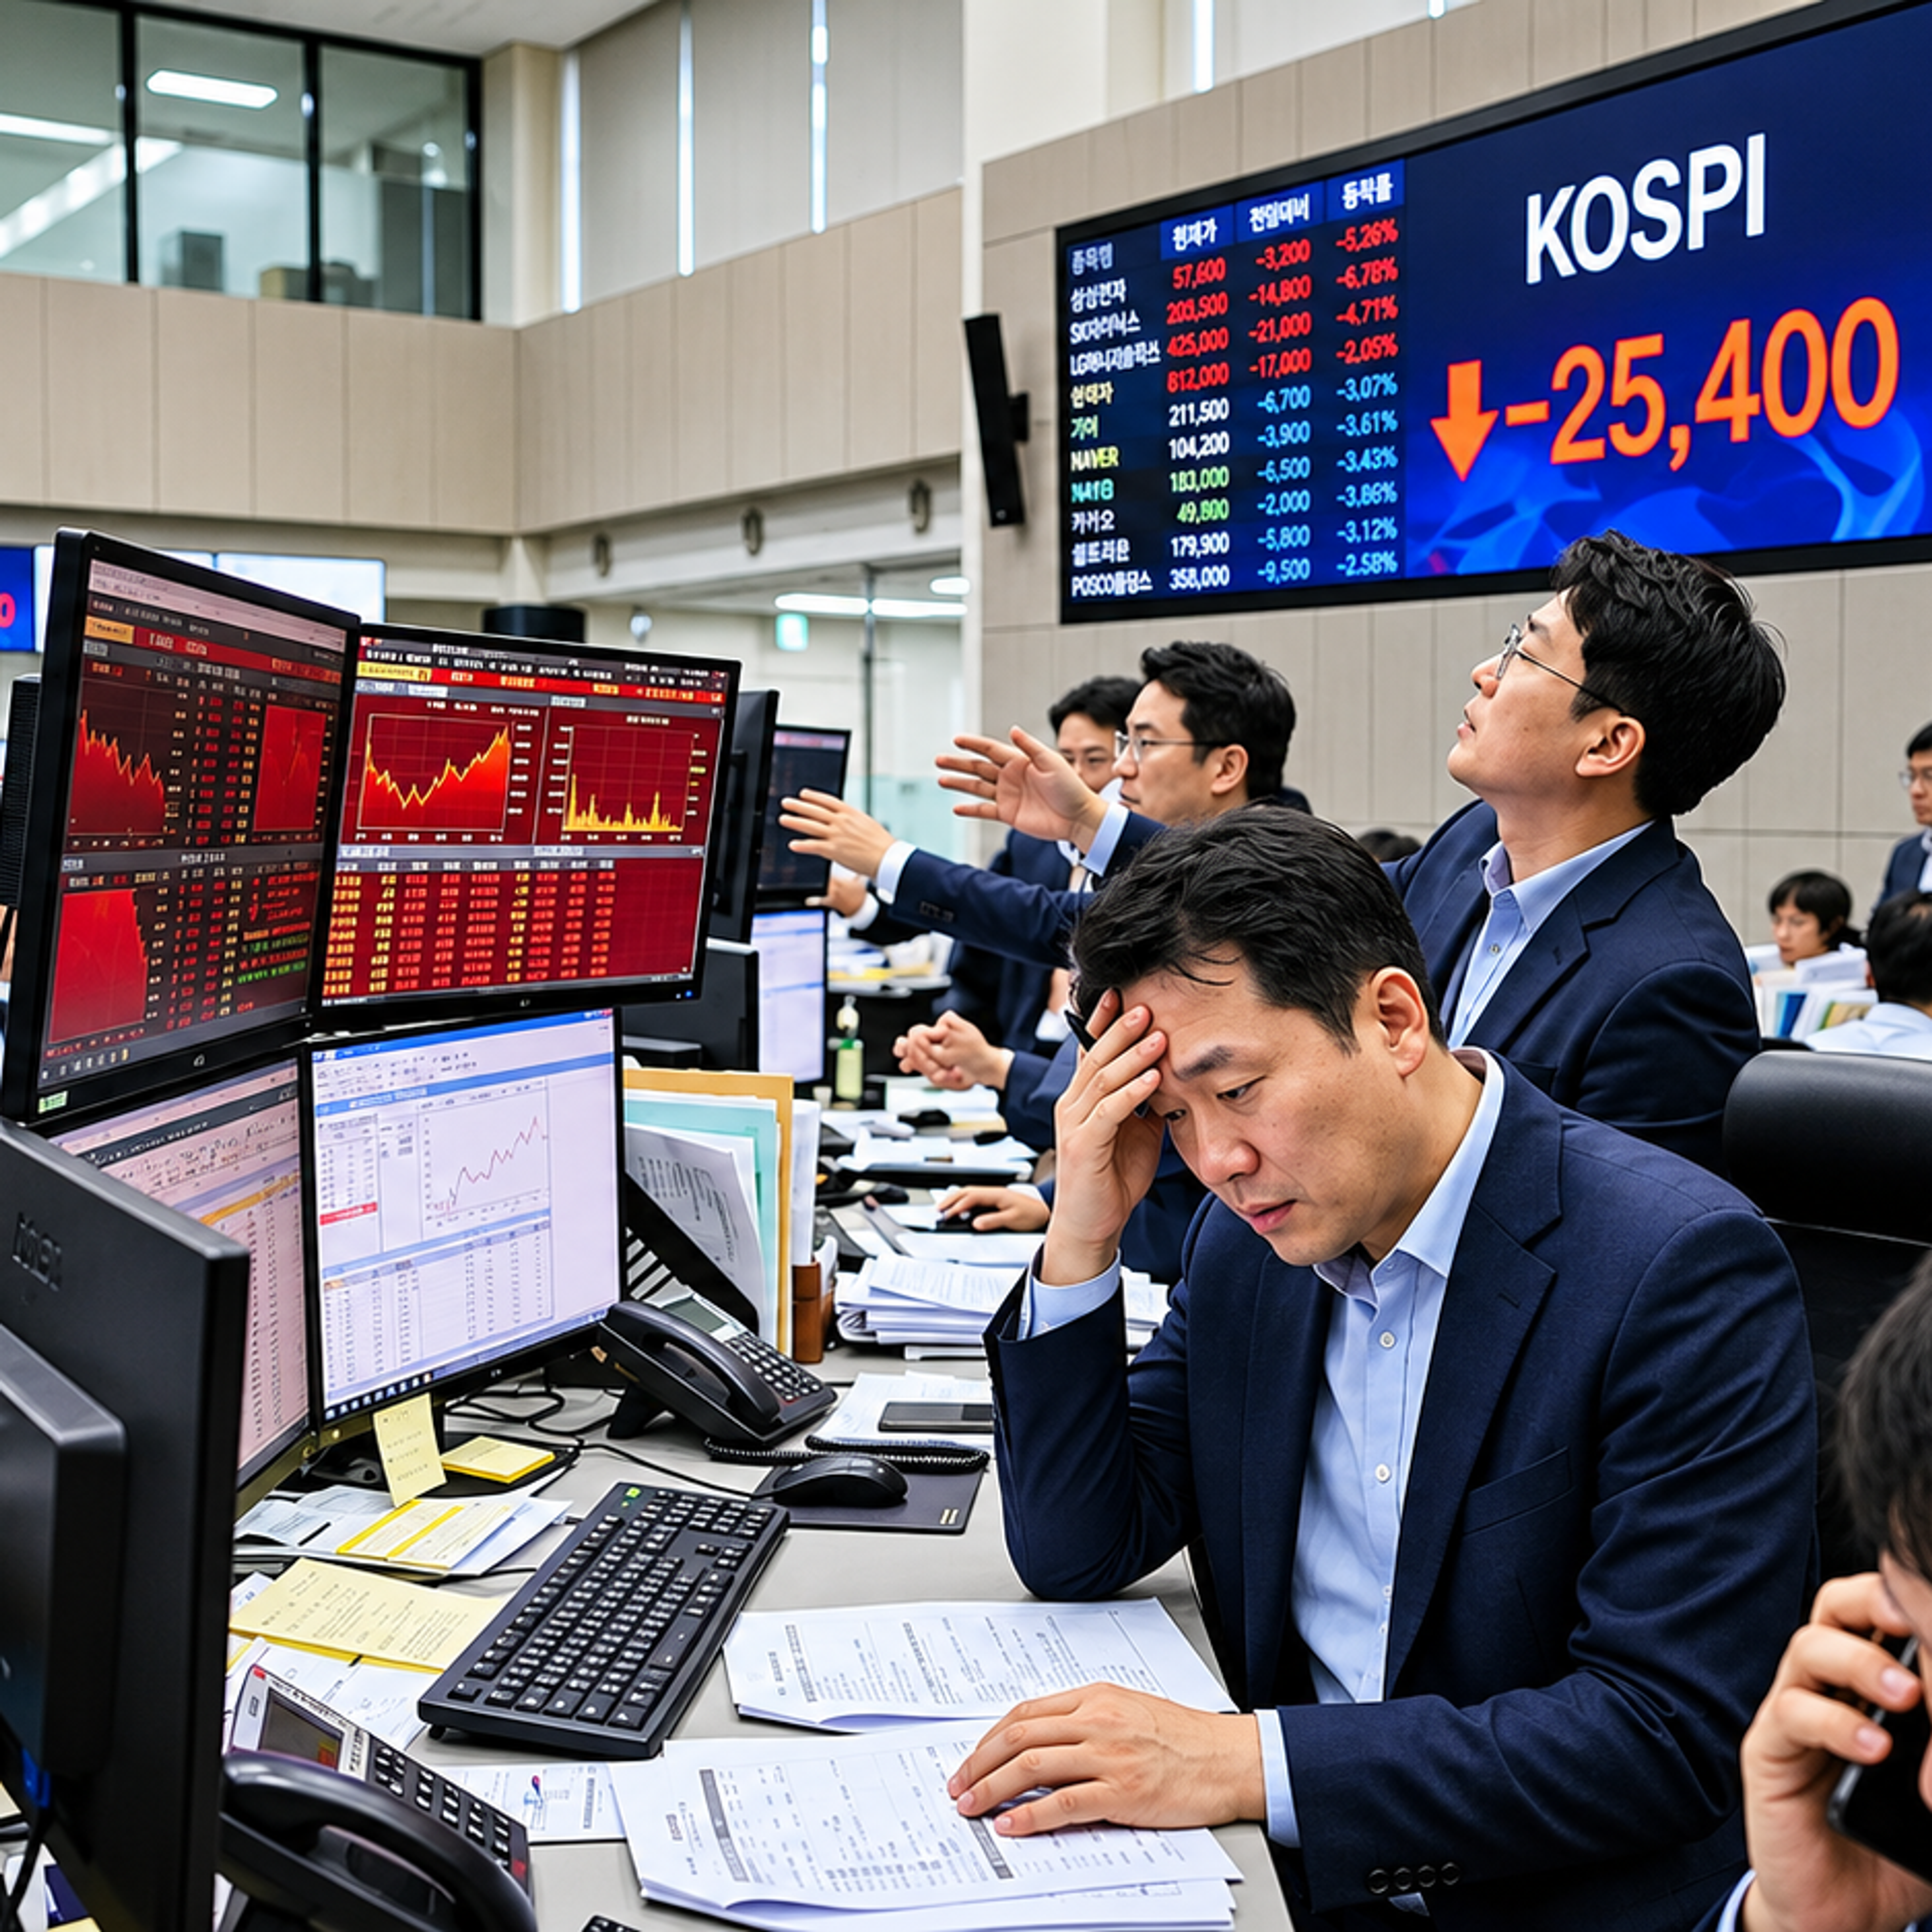
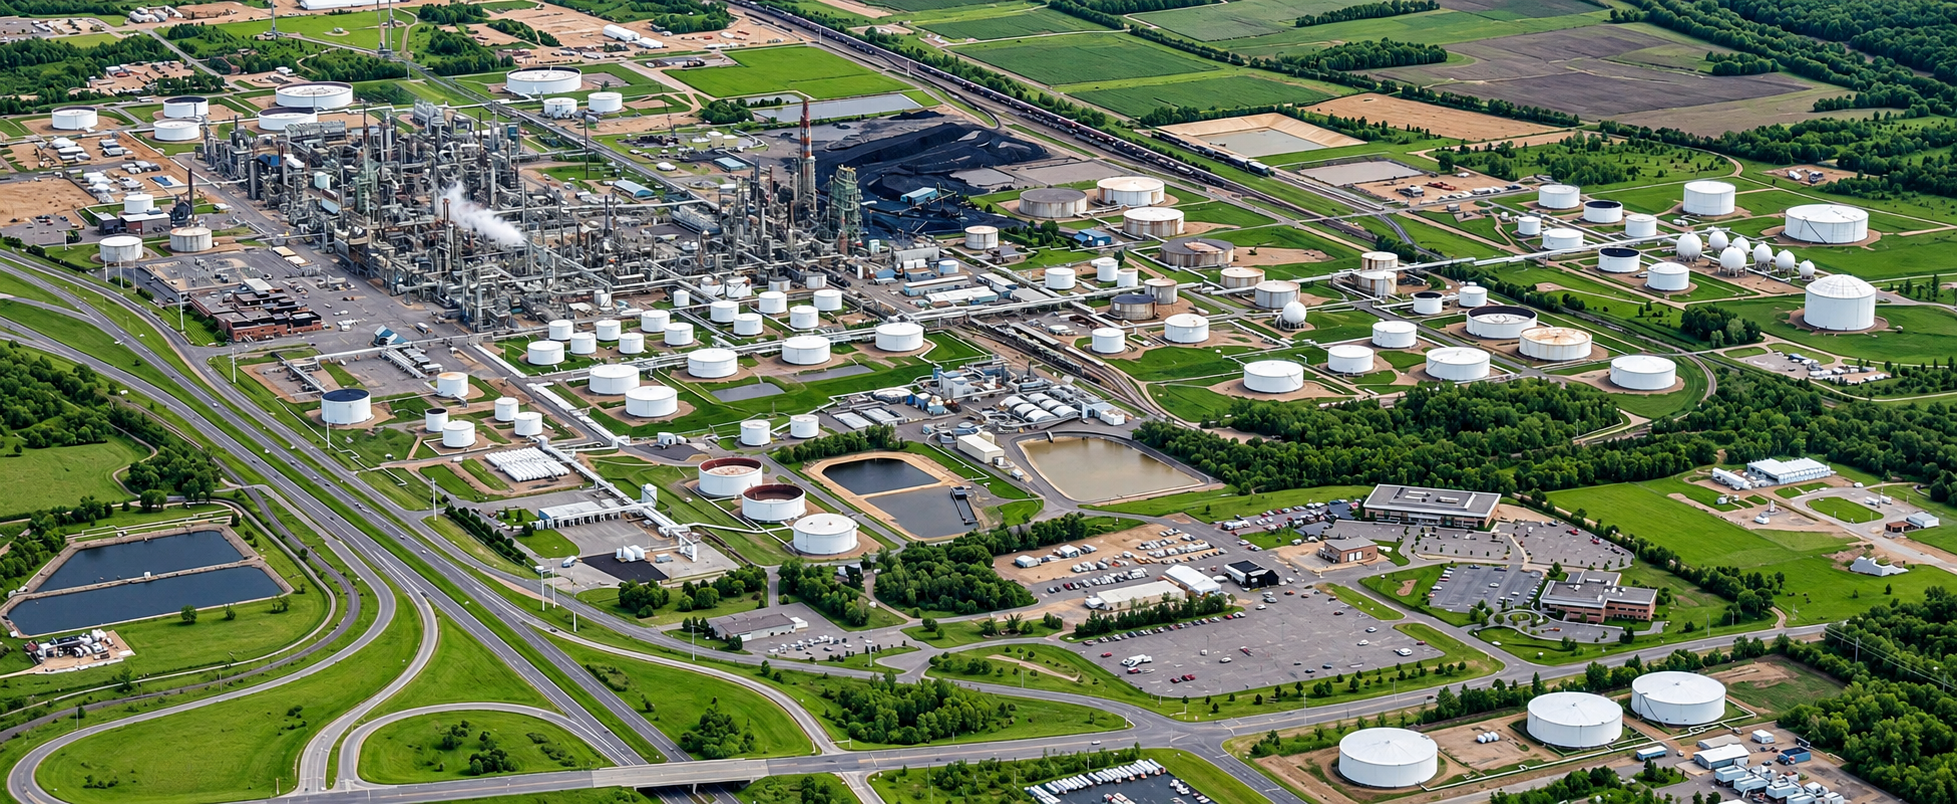
Oil prices plunged by more than 8 per cent on Wednesday (November 4), marking one of their steepest single-day falls in recent months, as markets reacted to Donald Trump’s midterm election defeat and began anticipating a possible diplomatic end to the eight-month war against Iran. Trump’s Republican Party suffered a sweeping electoral setback, with Democrats winning control of both the House of Representatives and the Senate. The result raised expectations that the President would face mounting political pressure to end the conflict.
The sharp fall reflected a change in how traders viewed the war and its impact on global oil supplies. The conflict disrupted Gulf exports, threatened shipping through the Strait of Hormuz, and drove crude prices higher. But as the election results became clear, traders began removing the additional cost they had built into oil prices to account for the risk of further military escalation. US benchmark West Texas Intermediate (WTI) crude futures fell $7.97, or 8.3 per cent, to settle at $88.12 a barrel. Brent crude, the global benchmark, dropped $8.98, or 8.7 per cent, to $94.62 a barrel. Both benchmarks closed at their lowest levels since August 31, highlighting how quickly political developments can shift global oil markets.
Vance made the first move
One of the most significant political reactions came from Vice President JD Vance, who openly blamed the Iran war for the Republican Party’s electoral setback. “The real reason we lost is obvious to almost everyone. The reason we lost is the war. The president himself said so last night,” Vance wrote on social media on Wednesday, in an unusually direct admission from a senior member of the administration. He also said Trump himself had acknowledged that the conflict had hurt the party politically.
Trump also stated that he had no immediate plans to strike Iran. Democratic leader Chuck Schumer also indicated that his party would use its new congressional majority to push for an end to the conflict. Control of Congress gives Democrats considerable influence over government spending and military funding, as well as the power to scrutinise the administration's decisions. These powers could make it politically and financially more difficult for Trump to sustain the war without congressional support.
Why did the geopolitical risk premium disappear?
The sharp fall in oil prices came from a quick unwinding of the geopolitical risk premium, the extra amount buyers are willing to pay because they fear a conflict could disrupt oil supplies. For months, traders had factored in the possibility that the US-Israeli war against Iran could escalate, threaten oil facilities in Gulf countries such as Saudi Arabia and the UAE, or disrupt shipping through the Strait of Hormuz.
The waterway is particularly important because roughly a fifth of the world’s oil supplies normally pass through it every day. Importantly, this additional cost is based on the risk of a disruption, not just on an actual shortage of oil. When traders believe that the threat of further escalation is declining, they can quickly remove that extra cost from their calculations. That is what happened after the US election results strengthened expectations of a possible diplomatic settlement. In other words, oil prices fell not because supplies had suddenly returned to normal, but because traders began to believe that the worst of the disruption might be behind them.
Gulf oil supplies remain below pre-war levels
Despite the growing hopes of diplomacy, the physical supply situation remains difficult. Gulf exports of crude oil, condensate and refined petroleum products, excluding liquefied petroleum gas, averaged 17.1 million barrels per day in October, according to ship-tracking data from Vortexa cited by Reuters. This was down from 18.9 million barrels per day in September and represented only around three-quarters of the region's pre-war export levels.
The figures underline how severely the conflict has affected oil shipments from one of the world's most important energy-producing regions. The disruption has also prompted Gulf countries to look for alternative ways to transport their oil. The United Arab Emirates is reportedly considering building a third oil pipeline that would allow it to move more crude outside the Strait of Hormuz, reducing its dependence on the vulnerable shipping route. The move highlights a concern that is unlikely to disappear even if the war ends. Gulf producers have been reminded of how easily a conflict can threaten their most important export routes, making energy security a priority well beyond any immediate ceasefire.
The broader market sell-off overshadowed an important development that could normally have pushed oil prices higher. US crude oil stocks fell by 865,000 barrels to 409.8 million barrels in the week ended October 30, according to the Energy Information Administration. Analysts had expected stocks to rise by 877,000 barrels. A fall in oil stocks usually signals tighter supplies and can push prices up. However, traders were more focused on the possibility of an end to the Iran war, which could eventually restore disrupted oil supplies.
The diplomatic path is clearer — but far from clear
For all the market optimism, analysts caution that Thursday’s price move may be running well ahead of the diplomacy. A senior Iranian official told Reuters that the two sides remain far from a deal. Qatar has stepped up mediation efforts after the election results, and Iranian officials have confirmed that back-channel communication through mediators is continuing. But the terms of any potential settlement remain deeply complicated.
Concerns remain about the shape of any eventual agreement. A deal that allows Iran to present the outcome as a victory - while leaving Trump politically weakened domestically - could generate fresh instability rather than durable peace. The administration will also face pressure from Israel and from hawkish voices within its own base, many of whom are unlikely to accept terms that fall short of significant Iranian concessions on its nuclear and regional activities. “The election changes the political calculus in Washington, but it does not change the positions of the parties to the conflict,” a senior trade analyst observed. “There is a long road between a risk-premium unwind and an actual ceasefire.”
The physical market, too, continues to reflect the ongoing disruption. Gulf shipping remains below pre-war norms, insurance premiums for tankers transiting the region remain elevated, and the UAE’s pipeline deliberations signal that regional producers are not yet ready to bet on a swift resolution. A diplomatic breakthrough, if it comes, will take time to translate into restored supply flows - meaning the relationship between political progress and oil prices is likely to remain volatile in both directions.
What it means for India — and the world
For the world’s major oil-importing nations, the price fall carries significant economic weight, and nowhere more so than India. India imported 246.6 million tonnes of crude oil in the financial year 2025–26, with import dependence reaching 88.7 per cent, according to data from the Petroleum Planning and Analysis Cell. Estimates cited by the Indian Express suggest the country imports between 1.8 billion and 2 billion barrels annually, meaning every sustained $1 decline in the price per barrel can reduce the national import bill by as much as $2 billion.
A prolonged fall in crude prices could ease pressure on the rupee, reduce inflationary pressures across transportation and manufacturing, and improve India's current account position — meaningful relief for an economy that has absorbed months of elevated energy costs. Whether those gains flow through to petrol and diesel pump prices, however, is a separate question. Domestic fuel prices in India also depend on the rupee-dollar exchange rate, refining and marketing costs, domestic taxation and the pricing decisions of state-owned oil marketing companies, which have historically been reluctant to pass on savings with the same alacrity with which they pass on increases.
The broader lesson of Thursday's session is about how completely geopolitical expectations can dominate commodity markets when a conflict sits at the centre of the global energy supply chain. Physical fundamentals — inventory draws, production figures, demand data — were not irrelevant on Thursday; they were invisible beneath the weight of a single election result. As one market veteran put it, oil is never just oil. It is, always and inescapably, politics in a barrel.